Buying your first home? Start here.

I'll explain the deposit, buying costs and how lenders assess what you can borrow, then show you how to apply that to your figures.
Jai Raynor

"It's not complicated, but you just need to understand the mechanics."

Jai Raynor · Principal Broker

Part 1

What the bank actually cares about

There are two main questions: do you have the money, and can you afford the loan?

$
Gate 1
The money

Do you have the deposit, and the costs on top?

%
Gate 2
The loan

Can you afford it, the way the bank measures it?

You can have all the deposit in the world, but without the income to service the loan, it doesn't matter.

Some buyers are deposit-limited. Some are servicing-limited. Some are both. The first step is working out which part needs attention.

Deposit-limited Servicing-limited Both

Tap the one that sounds most like you. I'll point you at the right first step at the end.

Read more: The two questions banks ask · Deposit vs borrowing power

Right, let's start with the deposit.

Part 2 · Gate 1

The deposit equation, and where LMI comes in

A $650,000 property illustrative only
a 95% loan ($617,500)
▲ above 80% LVR, LMI territory your 5% gap ▲
The gap (5% of price)$32,500
Stamp duty (varies by state) $17,350may be $0
Lenders Mortgage Insuranceoften added to the loan
Legals and other costs$3,000
Cash you may actually need $52,850$35,500

LMI usually isn't paid in cash upfront, and Part 3 covers situations where LMI may not apply.

● The threshold effect: at this price, first home buyers in most states pay reduced or even zero duty. Go over your state's threshold and the full amount snaps back. Same property, same 5% gap, very different cash needed.

1. LVR is how the bank measures risk. If you stop paying, the bank's way of getting its money back is selling the property. The bigger the loan against the property's value (the loan-to-value ratio), the more risk they carry. That's where the old you-need-20% wisdom comes from.
2. Above 80% LVR, LMI often becomes relevant. LMI is insurance that protects the lender, not you. It can add to the cost of buying with a small deposit, but the trigger, amount and whether it can be added to the loan depend on the lender and application. Hold this thought, because it explains Part 3.
3. Your deposit is not the cash you need. The real number is the cost to complete: the gap between what the bank lends and the full cost of buying. Stamp duty and fees sit on top of the price, and stamp duty swings hardest. Land under your state's first home buyer threshold and it can drop toward zero.
Cash you may need $52,850$35,500
Part 3 · Gate 1

Three options for a smaller deposit

The reason I explained LMI first is that it makes sense of all of this. Each pathway changes how the deposit or lender risk is handled, which may reduce the LMI hurdle or deposit requirement.

1. Government assistance
the government carries the risk
5% Deposit Scheme. The government guarantees the gap above your 5%, so LMI may not apply. Trade-offs exist: fewer lenders, and you might refinance out later.
Help to Buy. Shared equity from a 2% deposit. The government co-buys a share, so you only service the rest. The one scheme that helps both gates. Income caps and other eligibility rules apply. The Help to Buy calculator checks the income cap for you.
State grants and duty concessions. Every state and territory has its own grants and stamp duty breaks. That's the threshold effect from Part 2.
Saving through super
FHSS. A tax-advantaged way to save the deposit through super.
Worked example: Queensland
First Home Owner Grant (new homes up to $750,000)$30,000
Transfer duty on new builds (from 1 May 2025)$0, no price cap
First home concession, established homesunder $800,000
Potential duty saving, depending on priceup to about $24,525

Eligibility, residency rules and price caps apply, and every state draws its own lines. Figures verified September 2026.

2. Professional LMI waivers
the lender carries the risk

Some lenders may consider eligible professionals at up to 90% or 95% LVR without LMI. Occupations, registration, income, property rules and maximum loan amounts vary by lender.

A professional waiver can remove one cost of buying, but it does not guarantee approval or make a loan suitable. The full application still needs to meet the lender's current policy.

Who may be eligible
Each lender keeps its own list of eligible professions, income floors and LVR limits, and the lists differ a lot between lenders. That's exactly the kind of policy detail a broker checks across the market for you.
3. Family guarantors
your family carries the risk

A family member offers part of their own property's equity as extra security. That may reduce the effective LVR enough that LMI does not apply, subject to the lender's policy and full assessment.

A guarantor helps when you don't have the money. It doesn't help if you can't afford the loan.

How it works, and the risk
Usually parents, and their equity is genuinely at risk if things go wrong, so it's a family conversation before it's a finance one. A guarantee may be able to be released once the lender is satisfied the remaining security and loan position meet its policy. Full explainer on the blog.

You still need to afford the repayments

With one partial exception, Help to Buy, every pathway above answers the money question. None of them fully answer whether you can afford the loan. That's the second gate, and it's where we go next.

Part 4 · Gate 2

Can you afford the loan, as the bank measures it?

Your borrowing capacity

No number shown on purpose. Yours depends on your circumstances.

── what you feel you could afford
what the bank may say, lifting as levers close

The real question in a strategy session: is the main issue borrowing capacity or the deposit?

1. The buffer. The bank tests you at a higher rate than the one advertised. That's why feeling you can afford it and hearing no from the bank can both be true at the same time.
2. Expenses have a floor. Lenders compare your declared spending with their living-cost benchmarks. A small reduction in spending may not change the amount they use.
3. Income type matters. PAYG, self-employed and casual income are treated differently, and differently again between lenders. Two people on the same money can have very different capacity.
Changes to income or debts can affect borrowing capacity. I can compare how much difference each change might make under different lenders' assessments. Here are some examples:
✓ Closing or paying out a car lease
✓ Lowering a credit card limit
✓ Reviewing how lenders treat HECS and other commitments, because policy differs between lenders
✓ A partner moving to permanent hours
Capacity

Other options depend on your circumstances and need an individual assessment.

Jai Raynor

A calculator can give you a rough range, but a lender still assesses your full circumstances. In a strategy session, I can work through the same framework using your actual numbers.

Part 5 · Both gates together

Work through your own figures

In a free strategy session, we can work through your income, debts and deposit together.

I'll check whether the main constraint is your deposit or borrowing capacity, compare the options and explain what needs to happen before you apply.
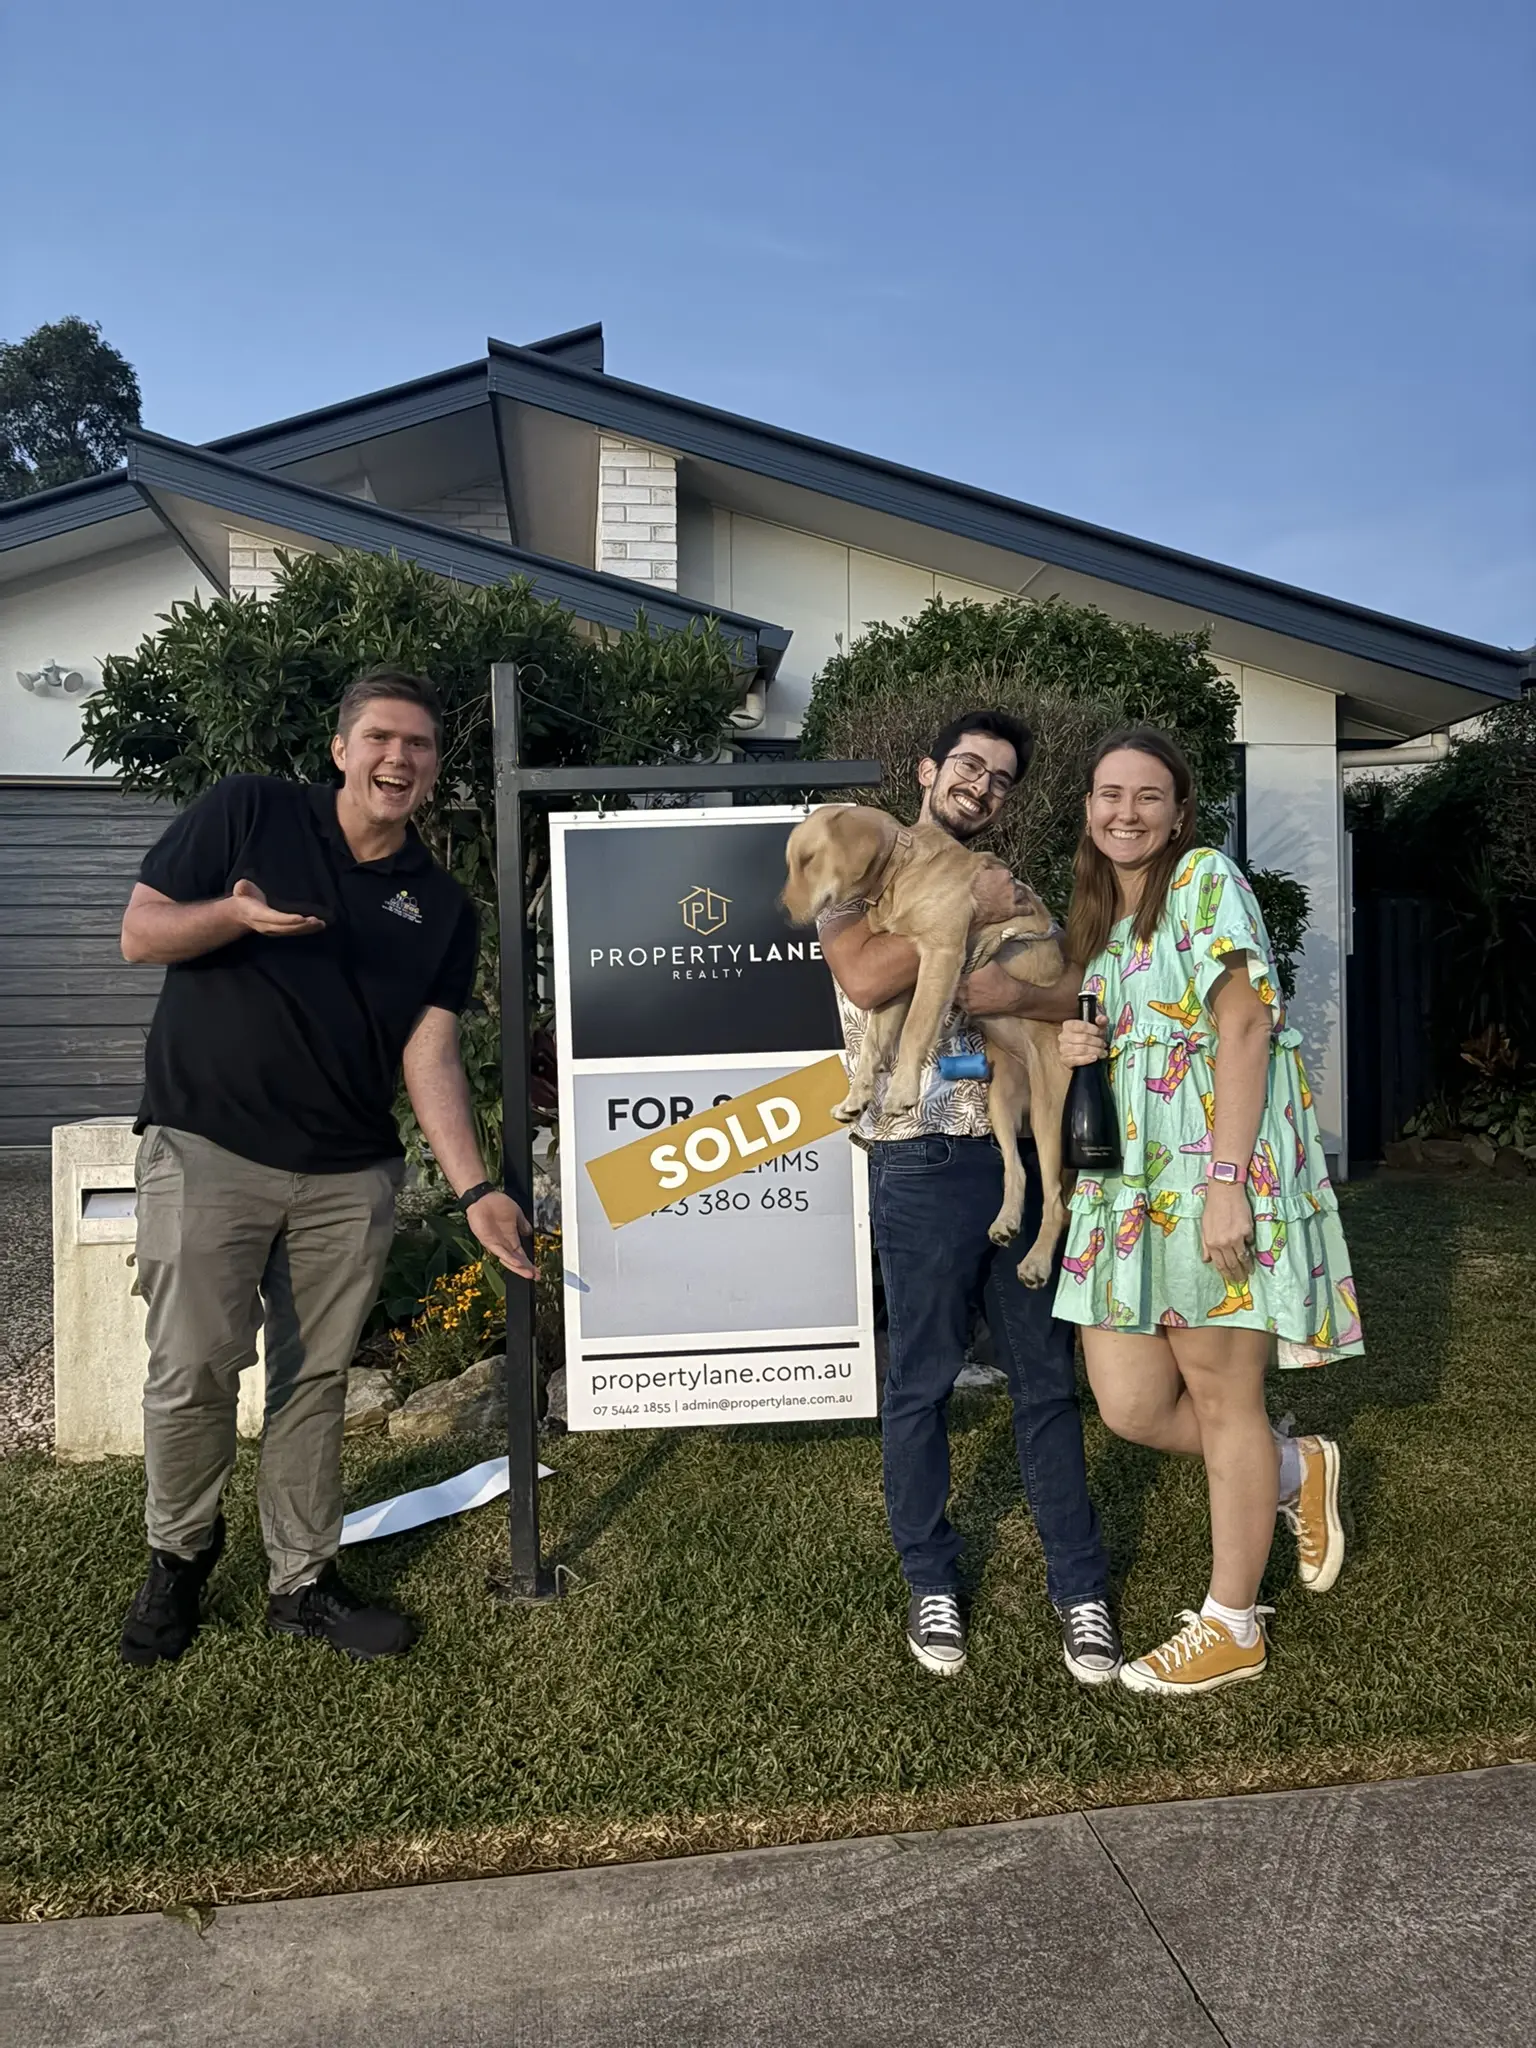
Jai with clients at their sold home
Book a free strategy session

It starts with a quick chat so we can make sure a session is worth your time.

Not ready to talk? Build your full cash checklist, put your numbers in the cost to complete calculator, take the eGuide (PDF) with you, or keep reading on the blog.

General information only, not personal credit advice. All figures are illustrative and depend on your circumstances. Scheme rules and figures change, check current details or ask me.